TLDR
The article covers the shift to SORA for home loan rates, urging consideration of refinancing options amidst rising rates. It highlights the impact of elevated rates and floor rates, potential penalties for property sales post-refinancing, and the influence of rising fixed deposit rates on loan costs. The timeline of loan acquisition is emphasized, suggesting staying put if acquired during low-rate periods. Extending the interest rate period during hikes is advised, along with choosing between fixed and variable rates based on upgrade plans. Market uncertainty prompts caution, recommending strategic real estate advice for clarity. The piece emphasizes the importance of understanding these factors to navigate the evolving home loan landscape effectively in 2024.
As we step into 2024, the average home loan interest rates are hovering somewhere around three per cent. Don’t be surprised if you see many loan deals slowly climbing to about four per cent in subsequent years, typically from the fourth year onwards. Now with the recent shift to SORA-based loans, a lot of homeowners are scratching their heads, wondering if it’s high time to scout for a more affordable loan plan. So, here’s the lowdown that you might want to consider before making your move:
Unveiling the Magic of SORA Conversion Packages
Our intention for penning this piece is largely influenced by the transition to SORA. As the new index set to supersede SIBOR, SORA will be the determinant of home loan interest rates moving forward. Chances are, you’ve already received a communiqué from your bank, extending conversion packages.
It’s key to remember that sticking with SIBOR isn’t an available choice and inaction on your part will result in an automatic conversion as of 1st June this year.
Moreover, if you opt for a loan switch due to the shift, but later have qualms about it, banks offer the provision for another one-time complimentary switch. This proposition is valid until the curtain falls on this calendar year, the 31st of December.
An important consideration is that new loan constraints won’t be relevant if you choose a loan package from your existing bank. So, if your home loan was procured a decade or more ago, prior to amendments like the decreased LTV ratio or the TDSR framework, the bank isn’t obligated to reassess your loan eligibility. If refinancing is on your agenda, the process would be less cumbersome if tackled immediately.
However, should you decide to refinance with a completely different bank, they will certainly verify your eligibility based on the new constraints.
Top Concerns When Refinancing in 2024
Unveiling the Impact of Elevated Interest Rates and Floor Rates
Alright, let’s break this down. We’ve talked before about how the uptick in interest rates is causing some worry, right? Now, with home loan rates on the rise, it might be a good idea to lock in a fixed rate or snag a lower rate package while the SORA conversion is still an option.
There’s another thing to keep in mind here – the base rate used for figuring out TDSR. It’s set at four per cent, a bit higher than actual home loan rates. This is to make sure that if rates do go up, borrowers will still be able to manage. But, some folks who got their loans a while back have a lower base rate of 3.5 per cent and a higher TDSR limit, which means they could make repayments up to 60 per cent of their monthly pay (nowadays it’s down to 55 per cent).
Looking ahead, rising rates and prices might push the base rate up even more, and there could even be measures to lower the TDSR limit. We also gotta think about how TDSR comes into play with other loans, like car and education loans. If the repayments for those loans go up because of increased interest, well, that could mess with your ability to meet TDSR limits too.
So, all things considered, it might be smoother sailing to refinance now while you’re still ticking all the boxes, instead of waiting and potentially facing rougher waters down the line.
Property Sale Post-Refinancing Waiver Less Likely
In the good old days, this wasn’t a problem, but lately, a lot of refinance deals don’t come with a get-out-of-jail-free card if you sell your property right after refinancing during the lock-in period, usually 1 to 2 years.
You’re usually looking at a penalty of about 1.5% of the remaining loan amount, but let’s be real, every bank is different.
So, here’s the deal: If you’re kicking around the idea of selling your property, make sure you take into account that penalty fee or do the math on the cost and timeline if you decide not to refinance. You might have some wiggle room to negotiate this fee waiver when you refinance, but remember, your success might change depending on where you bank.
3 Ways Rising Fixed Deposit Rates Can Impact Your Loan Interest Costs
As interest rates take an upward swing under the influence of key players like the Federal Reserve, there’s a parallel shift in fixed deposit rates. A clear illustration of this was last year when we witnessed fixed deposit accounts reaching close to four per cent in some scenarios.
Now, this trend rings alarm bells for those whose board rates are linked to fixed deposit rates. In loan packages of this sort, the interest rate isn’t tied to an index such as SORA but to the lender’s fixed deposit offerings. Theoretically, this would discourage steep interest rates, given that the lending bank would have to increase its payouts (in terms of fixed deposit interest) to hike your home loan rate.
This theory held water in the era of low interest rates from years past; however, with the current rate hikes, it’s prudent for borrowers to evaluate their present board rates against the floating rate packages available. If we take a trip down memory lane to December 2022, we’ll remember the wave of grievances following DBS’s decision to up the ante on fixed deposit interest rates in response to rising general interest rates.
The effects on loans based on fixed deposits from the bank (FHR loans) are quite evident here. It’s a noticeable increase.
Therefore, taking into account the more substantial interest rate scenario in 2024, the once perceived safety of fixed-deposit based board rates might not hold true any longer.
Discover the Timeline of Your Current Loan Acquisition
Suppose you secured your home loan during a time when interest rates hit rock bottom, like the 2020 Covid outbreak period. In that case, it might not be necessary to consider refinancing. The likelihood is, today’s market may not present many, if any, packages that can compete with what you currently have.
As for the SORA conversion, you could potentially gain more by leaving things as they are and not taking any action – it would still switch over to SORA, possibly at a significantly lower spread. However, if you’re feeling unsure, it wouldn’t hurt to get some advice from a mortgage broker.
5 Reasons Why Extending Your Interest Rate Period Could Be a Smart Move During Rate Hikes
The concept of an interest rate period simply points to the duration before your rates are adjusted in accordance with the corresponding index. For example, a one-month SORA rate (1M SORA) essentially means that your rates will undergo alterations every month. Conversely, a three-month SORA rate (3M SORA) implies a quarterly adjustment.
In situations where interest rates are moving upwards, it usually makes sense to switch to an option with a longer interest rate period. To put it in perspective, if interest rates are climbing monthly, you’d ideally want to stick to the interest rates from the previous quarter as opposed to the current rates.
Conversely, when rates are on a downward slope, you’d prefer monthly revisits to your rates. Therefore, if you secured your loan package during a period of falling interest rates, it might be wise to contemplate a shift for the next one to three years.
Has the 2024 Housing Market Altered Your Home Upgrade Strategy?
If you’re considering an upgrade in the next few years, it might be smarter to stay with the lower interest rates offered by a variable-rate loan. Selling soon means your priority should be keeping your interest payments low for now.
(Just remember, fixed-rate home loans usually cost more than their variable-rate counterparts)
On the flip side, if hefty private property prices have got you thinking twice, then perhaps the opposite approach is best for you. If you’ve decided to stay put for the foreseeable future, consider refinancing into a fixed-rate loan for stable monthly repayments or go for a loan package with the lowest rate from the fourth year onwards, considering your extended stay.
A good rule of thumb we’d suggest is for homeowners living in their properties to opt for fixed rates that offer predictability, rather than chasing seemingly lower short-term rates (a strategy better suited for investors with shorter term plans). Yes, it might cost a tad more, but at least you won’t face a sudden jump in your home loan rate.
Right now, the home loans market is a bit of a puzzle: it’s unclear whether rates will dip due to the broader economic climate, or if the Fed will hold steady – or even hike – interest rates to tackle inflation concerns. It’s a great time for homeowners to tread cautiously. Plus, if you stay with your current bank, you can switch your loan type for free at the end of the year, so why not try a more conservative approach?
Should You Buy, Sell or Wait?
If you’re reading this, you must be trying to figure out the best course of action right now: is it the right time to buy or sell?
It’s difficult to give an exact answer since everyone’s situation is unique and what works for one person may not necessarily work for you.
I can bring you a wealth of on-the-ground experience and a data-driven approach to provide clarity and direction. From beginners to experienced investors, our top-down, objective approach will help you on your real estate journey.
I can help you by:
- Offering Strategic Real Estate Advice – I can help create a comprehensive plan to guide you through your property journey.
- Connecting Your Home with the Perfect Buyers – Through stunning visuals, an effective communication strategy, and an in-depth knowledge of the market, we’ll ensure your home is presented in the best possible way to fulfill your goals.
You May Also Like …
Jayson Ang – September 13, 2026 – Share
TLDR For HDB owners eyeing new launch condos, upgrading often means trading space for modern amenities and potential long-term value....
Read More
Jayson Ang – July 14, 2024 – Share
Singapore's prime district properties continue to be in high demand due to a combination of factors that make them attractive...
Read More
Jayson Ang – April 6, 2026 – Share
TLDR District 15 condos show a nuanced split between old and new developments. Freehold projects have driven much of the...
Read More
Jayson Ang – July 12, 2023 – Share
Top 5 Must-Try Foods in Singapore Singapore, a melting pot of cultures and cuisines, offers a diverse and tantalizing array...
Read More
Jayson Ang – August 5, 2023 – Share
TLDR When aiming to purchase a home, it is crucial to gain knowledge about the buying process and track your...
Read More
Jayson Ang – August 25, 2026 – Share
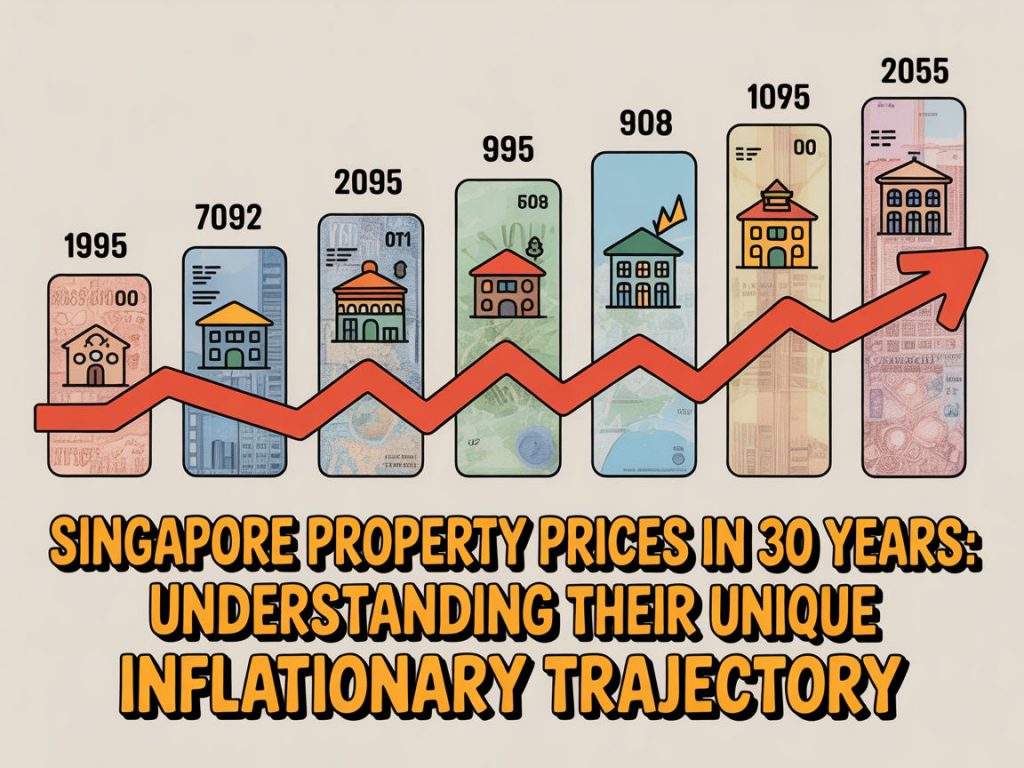
TLDR Singapore’s property market has shown a unique inflationary trajectory over the past 30 years, consistently outpacing general consumer inflation....
Read More
Jayson Ang – February 18, 2025 – Share
TLDR Rentvesting is a strategy where individuals rent a home in their desired location while purchasing investment properties in more...
Read More
Jayson Ang – November 9, 2025 – Share
TLDR Undervalued properties are harder to find in Singapore due to market transparency, but deals still exist. Target areas with...
Read More
Jayson Ang – April 16, 2026 – Share
TLDR Singapore’s executive condominiums (ECs) have improved significantly, now matching private condos in design and facilities but at lower prices....
Read More
Jayson Ang – January 26, 2024 – Share
TLDR The Singapore property market is experiencing shifts with Morgan Stanley adjusting its outlook on major developers. A forecast predicts...
Read More
Jayson Ang – January 4, 2024 – Share
TLDR This blog post delves into various aspects of the Singapore property market, including topics such as decoupling, 99-1 property...
Read More
Jayson Ang – May 20, 2023 – Share
TLDR When considering property investments, understanding your motives is crucial. Factors like accessibility to amenities, remaining lease, transaction history, rentability,...
Read More
Jayson Ang – February 13, 2023 – Share
TLDR Jayson Ang discusses the essential factors to consider when seeking a property for investment. By analyzing the safe entry...
Read More
Jayson Ang – June 16, 2024 – Share
TLDR The 2024 Budget introduces changes to property tax bands, aiming to ensure fair taxation based on Annual Value (AV)...
Read More
Jayson Ang – May 24, 2026 – Share
The "Sell One, Buy Two" strategy gained popularity in Singapore after the Additional Buyer's Stamp Duty (ABSD) was introduced in...
Read More
Jayson Ang – March 18, 2026 – Share
TLDR NM’s family chose to buy a 4-bedroom unit at the new launch Lentor Mansion despite elevated condo prices, after...
Read More
Jayson Ang – March 9, 2024 – Share
TLDR In a nutshell, the Singapore property market is undergoing significant changes, with the introduction of a new housing classification...
Read More
Jayson Ang – March 13, 2024 – Share
With a highly competitive property market, it's crucial to choose a property developer that you can trust to deliver quality...
Read More
Jayson Ang – March 6, 2026 – Share
TLDR The impact of the new integrated development, Sengkang Grand Residences, on nearby condo prices was studied by comparing it...
Read More
Jayson Ang – December 3, 2024 – Share
The Singapore property market is known for its high-quality residential properties, attracting both local and international buyers. Luxury real estate...
Read More