Craving Dream Homes in the Urban Jungle: The Singaporean Dilemma Unveiled
TLDR The housing landscape in Singapore reflects evolving aspirations and desires, especially among the younger generation. Owning private property is...
Read More
TLDR
Understanding the complexities of upgrading from an HDB flat to a private property in Singapore involves selling your HDB flat first and managing cash flow effectively. Key steps include selling your HDB flat, issuing an Option-To-Purchase, and then searching for a private property. Carefully compute your cash flow timeline, including refunding CPF amounts and meeting down payment requirements. Remember legal fees and agent commissions when transitioning to a private property.
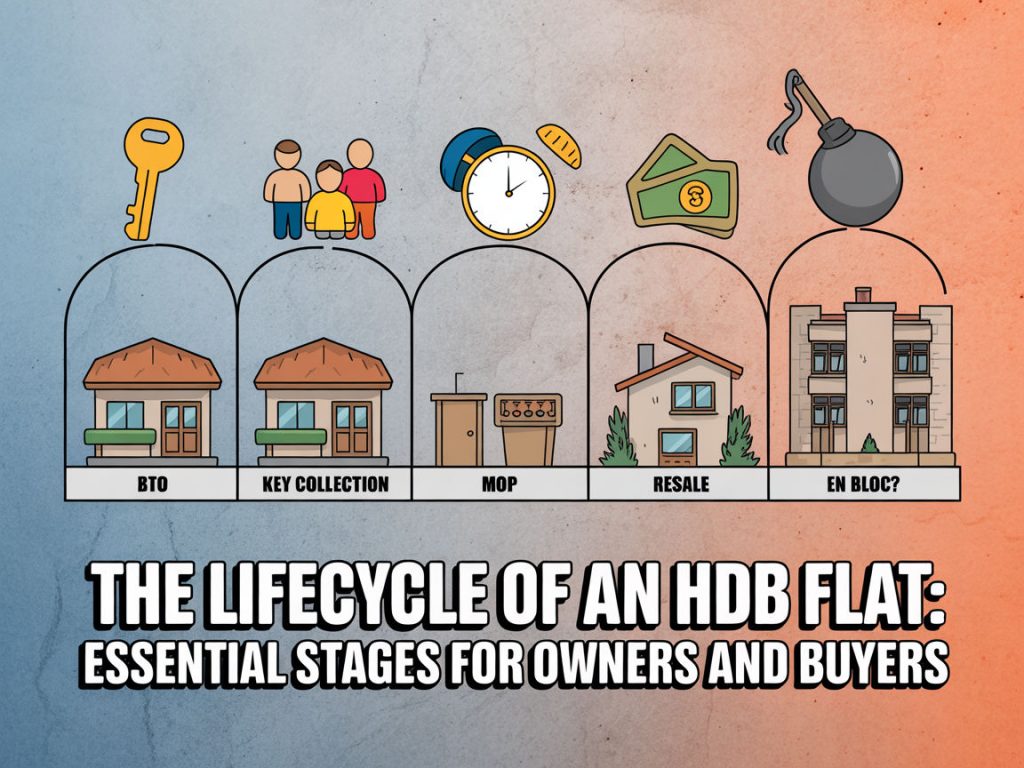
Having a dream of upgrading from an HDB flat to a private property is not an uncommon one for those living in Singapore – after all, about 80% of the population lives in HDB flats!
While buying your first HDB flat may have been a relatively smooth experience, taking the next step towards a private property is a far more daunting task. If you thought it would be just as easy, you might be taken aback by the reality of the situation – upgrading from an HDB flat is not nearly as simple as it seems.
When buying your first HDB flat, one of the biggest concerns is ensuring you can fulfil the down payment requirements. If you opt for an HDB loan, the minimum down payment is 10%, whereas if you decide to go with a bank loan, you’ll need to put down 25% with 5% in cash. This is why many buyers often opt for the HDB loan, even though interest rates are higher at 2.6% p.a.
Upgrading from an HDB flat to a private property can be a complicated process, with a greater chance of things going wrong if you’re not careful. To move forward, you’ll need to put your current HDB flat up for sale – a key step in the journey to owning a private property.
Generally, when looking to make the move from an HDB flat to a private property, it’s wise to start by selling the existing flat first. That way, you’ll know exactly how much you’ll receive and what you can and cannot afford. Plus, it’s essential to sell your HDB flat within 6 months, otherwise you may have to pay a 12% Additional Buyer Stamp Duty (ABSD).
The last thing you want is to be stuck in a tight situation, where you have to sell your HDB flat in a hurry to get your ABSD remission, only to be forced to accept a less-than-desirable offer.
No matter the timeline of your HDB flat sale, if you purchase a private property for $1 million, you’ll still need to cough up the 12% Additional Buyer’s Stamp Duty, that’s $120,000 out of pocket. In other words, if you haven’t sold your HDB flat upon exercising the option to purchase the private property, you’ll need to pay the 12% ABSD in cash first.
If you’re looking to put your HDB flat on the market, it’s best to enlist the help of a real estate agent. Before deciding who to go with, be sure to review the key details you need to cover in your discussions, such as commission costs and the terms of exclusivity. To help you out, here’s a checklist of the top 10 Traits of a Good Real Estate Agent.
Be sure to register your intent to sell your HDB flat with HDB first. Your agent should be able to advise you, but just in case they don’t, remember that you must grant an Option-To-Purchase (OTP) to buyers at least 7 days after registration. The process of finding a suitable offer could take anywhere from days to weeks or even several months depending on the area and your asking price.
Once you’ve secured an offer you’re happy with, the next step is to grant an Option to Purchase (OTP) for your HDB flat. An option fee of between $1 and $1,000 is payable – a much smaller sum than what you’d expect when buying a private property, which is usually at least 1% of the agreed price. So, remember to keep your expectations in check – although $1,000 isn’t an insignificant amount, the buyer may still back out and the fee is lost.
Possible factors that might cause buyers to withdraw could include:
Lower Valuation Report. If the HDB’s valuation report values your flat at $450,000, but the buyer agrees to purchase it for $500,000, the difference of $50,000 is referred to as cash over valuation (COV) and must be paid upfront. Unfortunately, since HDB only conducts the valuation after the Offer to Purchase is issued, this creates an element of uncertainty for both buyers and sellers.
If you have already issued an OTP for the buyer, keep in mind that it does not stop them from searching for other options that may suit their needs better. For example, an committed buyer may find an HDB flat at the same block/level as their parents that is similarly-priced, so they may decide to go with that option instead, even if they have already paid an option fee. Additionally, they may also find a cheaper flat even after accounting for the option fee. Therefore, it is important to be aware that better offers may be available elsewhere.
During this time, you can’t grant another buyer with an OTP. If your buyer doesn’t exercise their OTP within 21 business days, the option will expire and you can issue the OTP to other buyers. To exercise the OTP, the buyer must provide you with a Option Exercise fee which mustn’t exceed $5,000.
Once the OTP has been exercised for your HDB flat, you are then free to begin the search for your ideal private property. With the selling price of your HDB flat already known, and the cash proceeds from the sale in hand, you will also be aware of the time frame in which to hand over your keys to the new owners. All of this acts as a timeline, allowing you to comfortably seek out your perfect new private property.
Once an agreement to sell your HDB has been issued and finalized, it is no longer considered as a residential property that you own. In other words, if you purchase a private property after the OTP for your HDB has been exercised by the buyer, you are exempted from paying Additional Buyer’s Stamp Duty (ABSD).
If you’re in a hurry to move into your new home, you’ll need to get the ball rolling on buying a private property. To help speed up the process, consider pre-selecting a few places within your budget range before you put your HDB flat up for sale. That way, as soon as you find a buyer, you can begin negotiations on the private property. Of course, if you have somewhere to stay while you look for a permanent place, then you can take your time and really find the perfect spot.
Upgrading from an HDB flat to a private property is a significant financial step, and managing the cash flow to do it smoothly requires careful consideration. For example, if you sold your HDB flat for $500,000 with a loan of $200,000, your proceeds would be $300,000. Of that amount, you would need to refund $150,000 to your CPF Ordinary Account (OA). To complete the transition, the private property purchase would then be $1 million.
Let’s assume the option for your HDB flat was exercised on January 1st. Subsequently, both buyers and sellers needed to submit a resale application to HDB, and they did so within two weeks on the fifteenth of January. Upon receiving the application, HDB will issue the results, given all documents are in order, in approximately three weeks – by the beginning of February.
After your HDB application is accepted, it will take around 8 weeks for it to be processed. That would mean the first week of April for you to have the $300,000 in disposable cash and CPF amount to purchase your private property. This is the estimated time frame, but it may take an extra week for the refund to be made to your CPF. All in all, you should have the full amount ready to use by mid-April.
The purchase of a private property involves a crucial cash flow timeline – after the HDB flat is sold for $500,000, with an outstanding loan of $200,000, you will be left with a sales balance of $300,000. On paper, that means you have $300,000 in cash and CPF available to cover the minimum down payment requirement of $250,000 (25% of $1 million).
If you’re looking to purchase a private property, you’ll typically need to put down an option fee of 1% of the price. This means that if the property is valued at $1,000,000, you’d need to have $10,000 in cash at the ready. The remaining 4% is usually due within two weeks, but you can always negotiate with the seller to extend the option period.
If you wish to exercise the option, you will require a total of $50,000 in cash. This means you’ll need the funds ready to secure and execute the OTP, or wait until April for the cash you get from selling your HDB flat. Additionally, you will need to pay the buyer stamp duty in cash, which comes to around $24,600 for a $1 million property. All in all, to secure the OTP, exercise the option, and pay the buyer stamp duty, you’ll need to have a cash outlay of $74,600 to purchase a $1 million private property.
If you have enough funds, you can begin your hunt for your own place and secure the OTP and exercise the OTP before April. If you do not have enough funds, however, you’ll need to wait for the proceeds of your HDB flat sale to arrive in your account before you can act.
It typically takes 12 weeks for completion of a private property purchase after exercising your option. For example, if your HDB option was exercised on 1st January and your private property option on 19th January, the completion date will be approximately 19th April – giving you ample time to receive proceeds from the sale of your HDB to cover the down payment of the private property.
Beginning with the sale of your HDB flat, the following table illustrates the timeline all the way up to the purchase of your private property.
The table above shows the timeline for receiving the full amount from the sale of your HDB flat and making the down payment for your private property is rather short. If you don’t have the necessary funds, it’s likely that you’ll have to postpone the completion of your private property purchase.
To fund your residential property purchase, secure the bank loan needed and hire a lawyer to assist with the conveyancing paperwork. Typically, legal fees range from $2,500 to $3,000. Also, don’t forget to pay the commission to your agent, which is normally taken out of the proceeds from the sale of your HDB flat.
You May Also Like …
A password will be e-mailed to you